 Analysis by Appwee
When it comes to managing your credit score and financial health, Intuit Credit Karma is like having a personal finance guru right in your pocket. I’ve been using this app for a while, and let me tell you, it’s become an essential part of my financial toolkit. Let me break down why this app might just be the game-changer you need.
What I’d check before relying on it
I think of Credit Karma as a convenient place to keep an eye on credit, not as a replacement for every financial account or for the records I keep myself. That distinction matters: a score shown in an app can help me notice movement and understand broad factors, but a lender may use a different scoring model when making a decision. If I’m preparing for a major application, I treat the app as a useful checkpoint rather than a promise of the exact number a lender will see.
Credit Karma is a free finance app from Credit Karma, LLC. It has a 4.7 average from around 3.1 million ratings, and more than 50 million installs. Those figures suggest it’s widely used, but popularity doesn’t make every recommendation right for every person. I’d still read an offer’s terms carefully and compare it with options from my bank or another financial service before acting.
The practical appeal is strongest when I want a quick, recurring look at my credit picture without building a complicated spreadsheet. It can help me frame questions—why a score changed, what information appears on a report, or whether I should pause before applying for another product. The app is less suited to someone who wants a full household budget, hands-on debt counseling, or one definitive score for every lending situation.
First Impressions and User Interface
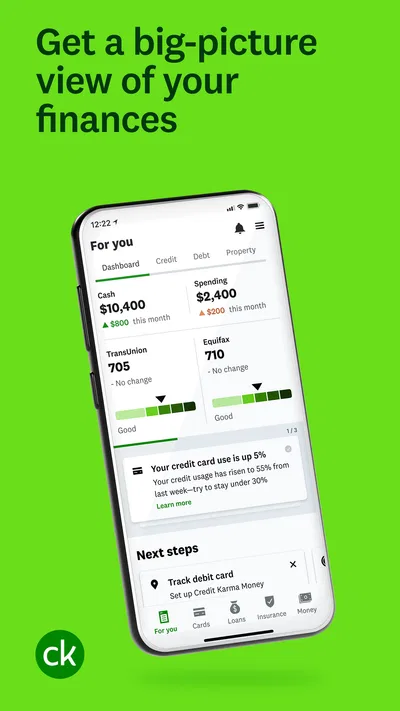
The first thing I noticed about Intuit Credit Karma is how sleek and user-friendly the interface is. As soon as you open the app, you’re greeted with a dashboard that’s as intuitive as it is informative. Everything is neatly organized, making it easy to navigate through your credit scores, reports, and personalized insights.
One of my favorite features is the visual representation of your credit score. It’s not just numbers; you get graphs and trends that show how your score has changed over time. This makes it super easy to understand where you stand and what you need to do to improve.
Features That Stand Out
Now, let’s dive into some of the standout features of the app. First off, you get free access to your credit scores from major credit bureaus, which is a huge plus. No more guessing games; you have the information you need right at your fingertips.
More From Our Writers

OTR Makes Off-Road Roaming a Perfect Fit for Short Play Sessions

Prime Video vs. Netflix and Disney+: More Choice, More Clutter

SHAREit Review: A Fast, No-Cloud Way to Move Files

Cryptoguru Makes Crypto Trading Safer, but Can It Teach Restraint?

FC Mobile 26 Turns Soccer into a Season-Long Service

Reddit Is Worth Your Time Only If You Choose Your Communities
Another cool feature is the personalized recommendations. Based on your credit profile, the app suggests financial products that might suit your needs, like credit cards or loans. It’s like having a financial advisor that knows your situation inside out.
Security is also top-notch here. The app uses advanced encryption to protect your data, which gives me peace of mind knowing my information is safe from prying eyes.
Reading scores and recommendations with care
A useful habit is to look at a score change alongside the factors and report details shown in the app, instead of reacting to the number alone. If I spot something I don’t recognize, I’d first compare the account or inquiry with my own statements and recent applications. That simple cross-check helps separate a legitimate activity I forgot about from something that deserves closer attention.
The recommendations are convenient, but I wouldn’t treat them as personalized financial advice in the human sense. They can put relevant-looking products in front of me, yet the final choice still depends on details such as fees, repayment terms, and whether I actually need another account. A practical approach is to use a recommendation as a prompt to compare, not as a reason to apply immediately.
That trade-off is central to the app’s role. Its credit information and product suggestions sit together, so I find it helpful to keep my purpose clear when I open it: checking my profile is one task; shopping for a financial product is another. If I’m only monitoring credit, I can focus on the report and score rather than letting an offer distract me from the reason I came in.
Real-Life Benefits
So, how does this app actually help in real life? For starters, it’s helped me stay on top of my credit score and understand the factors affecting it. I’ve been able to make smarter financial decisions, like when to pay off certain debts or apply for new credit.
I also love how the app alerts you to any important changes in your credit report. Whether it’s a new account opening or a hard inquiry, you’re immediately notified, which is crucial for keeping tabs on your financial health.
A routine that makes monitoring useful
For an everyday example, imagine I’m planning to replace an old appliance and expect to compare financing options. I can check my credit profile beforehand, review what accounts and inquiries are visible, and make a more informed decision about whether to apply now or wait. Afterward, a notification about a new inquiry can prompt me to confirm that it matches the application I made. The app doesn’t make the decision for me, but it gives me a practical sequence: check, compare, apply only if it fits, then review.
I’d also avoid checking repeatedly throughout the day. Credit information is more useful as a trend and as a way to catch changes than as a moment-by-moment measure of financial progress. A regular check-in gives me room to notice a meaningful shift, while reducing the temptation to overinterpret ordinary movement or chase a score with rushed applications.
If I find an unfamiliar item, I would not assume a notification alone resolves it. I’d verify it against my own account records and use the appropriate reporting or issuer channels to investigate. That is an important limit of any monitoring app: being alerted is helpful, but understanding and resolving a potential error may require action outside the app.
How it fits beside other money tools
Compared with checking a credit score through a bank, Credit Karma can feel more focused on bringing score information, report details, and product recommendations into one place. A bank’s own tools may be more convenient if I already manage my accounts there, while a dedicated budgeting app is usually the better fit for tracking spending categories, bills, or a monthly cash-flow plan. These tools solve different problems, so I wouldn’t replace a budget with Credit Karma or assume a bank’s score display provides the same experience.
For someone who wants to monitor credit at no cost, the free price makes it easy to try. The app is rated for Everyone, and its current version is 26.4; it was released on February 28, 2013, and requires operating system version 9 or later. Those details help set expectations about access, but they don’t tell me how it will feel on every individual device.
Speed, stability, and device expectations
In ordinary use, a finance app like this is most valuable when I can open it, orient myself, and find the relevant section without turning a quick check into a project. The dashboard-led layout described above supports that kind of short visit. I would still judge speed on my own phone and connection: loading account-related information can involve more than simply displaying a static screen, so I wouldn’t assume every page will appear instantly in every setting.
For heavier use—moving between score history, report details, and recommendations—I’d keep the session focused and give each section time to load before tapping around. If something seems stale or slow, a sensible first step is to refresh the view or reopen the app when the connection is steadier, then compare the information again. I wouldn’t interpret one delayed update as proof that the underlying report has changed or that the app has lost information.
Credit monitoring is also a category where reliability means more than a smooth animation. I want alerts to bring my attention to an item, but I still need to verify unfamiliar activity and keep independent records. If the app is temporarily unavailable or I need to make a time-sensitive decision, I’d use the relevant creditor or financial institution directly rather than wait on a single app. That backup habit is useful for any service handling important personal information.
On a device running an older supported operating system, I’d pay attention to whether the app remains comfortable to navigate and whether updates are available for that device. The minimum requirement is operating system version 9, but that alone doesn’t guarantee identical performance across phones. If my device struggles with newer apps generally, I’d keep expectations modest and avoid making this my only way to access important financial details.
The Bottom Line
In conclusion, Intuit Credit Karma is not just an app; it’s a gateway to financial empowerment. It’s packed with features that not only keep you informed but also guide you towards better financial choices. Whether you’re a credit newbie or a seasoned pro, this app has something valuable to offer.
So, if you’re looking to take charge of your credit score and improve your financial literacy, give Intuit Credit Karma a shot. It’s free, it’s insightful, and it might just be the tool you need to reach your financial goals. Trust me, your future self will thank you!
My performance verdict is measured rather than absolute: I’d use it as a convenient credit-monitoring companion, while keeping my expectations grounded about update timing, device differences, and the limits of any one score. It’s a good match for people who want a simple place to review credit information and consider possible next steps. If I needed detailed budgeting, personal guidance, or a lender-specific score before a major decision, I’d pair it with a tool or professional better suited to that task.
Intuit Credit Karma Pros and Cons
- User-friendly interface with intuitive navigation.
- Free credit score tracking and updates.
- Personalized financial recommendations.
- Secure and private data handling.
- Access to educational financial resources.
- Limited support for international users.
- Occasional in-app ads can be distracting.
- Some features require linking bank accounts.
- Not all credit reports are available.
- Information may not update in real-time.
Intuit Credit Karma Frequently Asked Questions
What is Intuit Credit Karma and how does it work?
Intuit Credit Karma is a personal finance app that provides users with free credit scores, reports, and monitoring. It works by accessing your credit data from major credit bureaus and presenting it in an easy-to-understand format. The app also offers personalized financial tools and recommendations, helping you make informed decisions and improve your credit health.
Is Intuit Credit Karma really free to use?
Yes, Intuit Credit Karma is completely free to use. The app makes money through targeted advertising and financial product recommendations, meaning you won’t be charged for accessing your credit scores or reports. However, it's important to note that while the app itself is free, the financial products it suggests may have their own costs.
How accurate are the credit scores provided by Intuit Credit Karma?
The credit scores provided by Intuit Credit Karma are generally accurate and sourced from major credit bureaus like TransUnion and Equifax. While these scores are a good indicator of your credit health, they might not always match the scores used by lenders, as different scoring models may be used. It's a useful tool for monitoring trends and changes.
What security measures does Intuit Credit Karma have in place?
Intuit Credit Karma uses advanced security measures to protect your personal information. This includes encryption, secure servers, and robust authentication protocols. They are committed to maintaining the privacy and security of user data, but it's always wise to use strong passwords and enable two-factor authentication for additional security.
Can Intuit Credit Karma be used outside the United States?
Intuit Credit Karma is primarily designed for users in the United States. While you may be able to access the app from outside the U.S., the credit reports and financial tools are tailored to the U.S. market. International users might not find the app as useful, as it may not support their local financial institutions.
Gallery